
Business suspension is a legal solution that allows an enterprise to temporarily halt operations for a certain period in order to restructure, resolve financial difficulties, or re-plan its strategy while still maintaining its legal-entity status. This procedure helps the enterprise avoid dissolution while optimizing its tax obligations during the period when no revenue arises.
Below is a detailed guide to the conditions, dossier, process, and key legal notes when carrying out the business suspension procedure, updated to the 2025 legal context.
Applicable legal basis
The procedure is carried out based on the following current legal documents:
- Law on Enterprises 2020 (and its amending and supplementing laws).
- Law on Tax Administration 2019.
- Decree 01/2021/ND-CP on enterprise registration.
- Decree 126/2020/ND-CP detailing a number of articles of the Law on Tax Administration.
- Decree 168/2025/ND-CP (Detailed regulations on enterprise registration – new document).
- Circular 68/2025/TT-BTC (Issuing the enterprise registration forms – new document).
- Decision 2354/QD-BTC dated July 3, 2025, of the Ministry of Finance on the announcement of administrative procedures.
Overview of Business Suspension
What is business suspension?
Business suspension is the legal status in which an enterprise, branch, representative office, or business location temporarily halts all or part of its business activities but still maintains its legal-entity status.
Unlike dissolution (permanent termination of existence), a suspended enterprise can resume operations at any time (before or exactly at the registered deadline).
During the suspension, the enterprise may not sign new contracts or issue invoices, but must still fulfill any financial obligations outstanding from before.
Conditions for carrying out business suspension
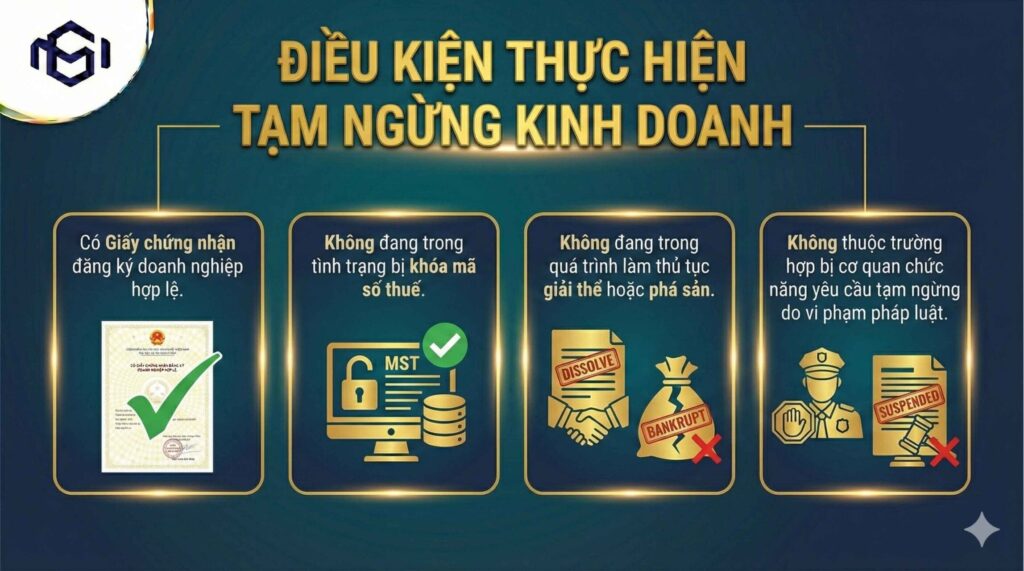
To obtain the state authority’s approval, the enterprise must meet the following conditions:
- Have a valid Enterprise Registration Certificate.
- Not currently have its tax code locked.
- Not currently be undergoing dissolution or bankruptcy procedures.
- Not fall into the case of being required by the authorities to suspend due to a legal violation.
Duration and frequency of business suspension
Duration per notification: No more than 01 year (12 months).
Number of renewals: Under current regulations, the law does not limit the number of consecutive suspensions. An enterprise may renew multiple times if it is still not ready to resume operations. However, each renewal must go through the procedure of notifying the business registration authority again.
Notification timing and processing deadline (New 2025 regulations)
Deadline for sending the notification
Under Clause 1, Article 206 of the Law on Enterprises 2020 and the guidance in Decision 2354/QD-BTC: The enterprise must send a notification to the Business Registration Office at least 03 working days before the date on which the business suspension begins (or before the date of early resumption of business). (Note: The old rule under the Law on Enterprises 2014 was 15 days; it has now been shortened to 3 days to facilitate businesses).
Dossier processing deadline
The business registration authority processes the dossier within 01 working day from the date it receives a valid dossier (under Decision 2354/QD-BTC).
If the dossier is invalid, the authority will issue a notice requesting amendment or supplementation. The enterprise has 60 days to complete the dossier.
Detailed components of the business suspension dossier
The enterprise needs to prepare 01 set of dossier with the following documents:
Common mandatory documents
- Notification of business suspension (Using Form No. 27, Appendix I issued together with Circular 68/2025/TT-BTC).
- Letter of authorization (if the legal representative does not submit in person):
- If authorizing an individual: A letter of authorization (notarization not required) together with a copy of the personal identification document (Citizen ID/Passport).
- If authorizing a service organization: A copy of the service contract and a letter of introduction from that organization assigning its staff to submit the dossier.
Specific documents by type of enterprise
The Notification must be accompanied by the Decision and meeting minutes of the highest competent body in the company:
- Single-member LLC:
- Resolution/Decision of the company owner.
- Multi-member LLC:
- Resolution/Decision of the Members’ Council.
- Copy of the Members’ Council meeting minutes.
- Joint-stock company:
- Resolution/Decision of the Board of Directors.
- Copy of the Board of Directors meeting minutes.
- Partnership:
- Resolution/Decision of the Members’ Council.
- Copy of the Members’ Council meeting minutes.
Process for carrying out the business suspension procedure (In person & Online)
Pursuant to Decision 2354/QD-BTC, the process is carried out as follows:
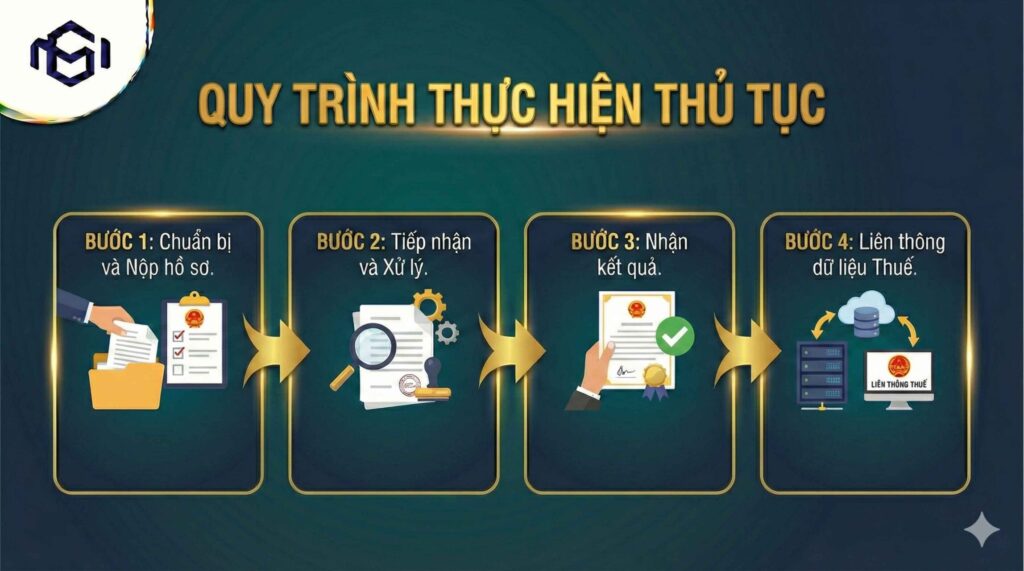
Step 1: Prepare and submit the dossier
The enterprise chooses one of the following submission methods:
Online submission (Recommended): Access the National Business Registration Portal (https://dangkykinhdoanh.gov.vn). The submitter uses an electronic identification account to log in, declare information, upload electronic documents, and apply a digital/authentication signature.
In-person submission: At the One-Stop Section – Business Registration Office under the Department of Planning and Investment (or the Department of Finance, depending on the locality).
Submission via postal service.
Step 2: Receipt and processing
After submitting the dossier, the enterprise receives a receipt (or an electronic dossier receipt with an appointment for the result).
The business registration authority checks the validity of the dossier within 01 working day.
Step 3: Receive the result
Valid dossier: The business registration authority issues a Confirmation of the enterprise’s registration of business suspension. At the same time, the system will automatically change the legal status of the enterprise and its dependent units (branches, representative offices, business locations) to “Business suspended.”
Invalid dossier: The enterprise receives a Notice to amend or supplement the dossier (clearly stating the reasons for the revision).
Step 4: Interconnection of tax data
The business registration authority will forward the suspension information to the Tax Authority. The enterprise does not need to submit a separate notification dossier to the tax authority.
The Enterprise’s Obligations During the Suspension Period
This is the most important part for avoiding later penalties or tax arrears.
Tax declaration and business license tax obligations
On tax declaration dossiers (VAT, PIT, etc.):
- If the suspension covers a full calendar month/quarter/year: The enterprise does not have to submit a tax declaration dossier.
- If the suspension does not cover a full period (e.g., suspending from the 2nd of January): The enterprise must still submit the tax declaration dossier for that period, even if it operated for only 01 day.
On the annual finalization report: The enterprise must still submit the annual tax finalization dossier for the period it operated during the year (before the suspension).
On the business license tax:
- Exempt from the business license tax for the year of suspension if: The suspension notification is sent before January 30 of that year and the fee has not yet been paid.
- If the notification is sent after January 30 or the fee has already been paid, it will not be refunded.
Financial and contractual obligations
During the suspension, the enterprise must:
- Pay all outstanding taxes (if any) before the suspension begins.
- Continue paying debts and completing the performance of contracts signed with customers and employees (unless otherwise agreed with the relevant parties).
- Not sign new economic contracts and not issue invoices for goods/services.
Special cases and new notes from 2026
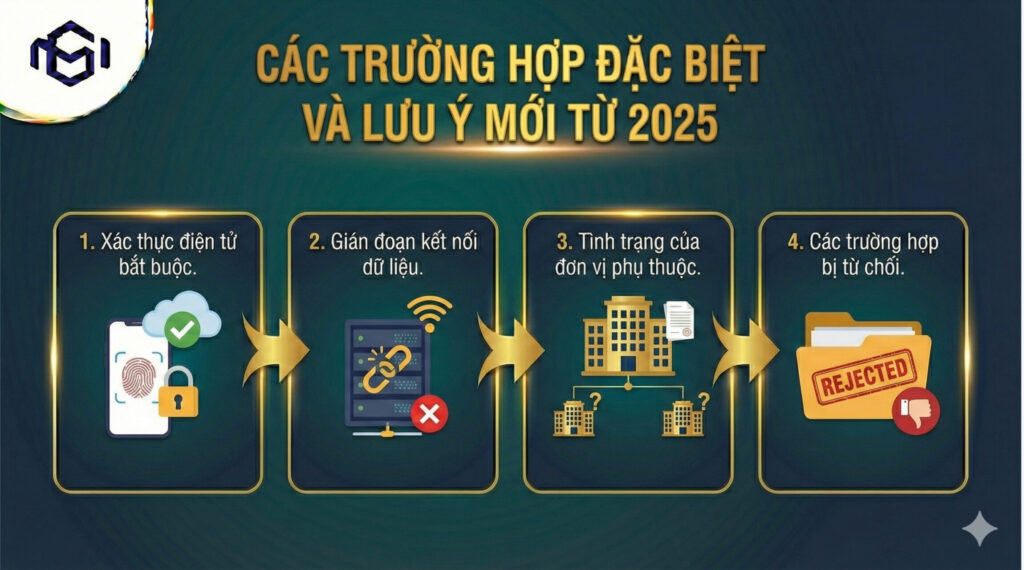
Under Decree 168/2025/ND-CP and Decision 2354/QD-BTC, there are several new points enterprises should note:
1. Mandatory electronic authentication: The submitter, the authorizing party, and the authorized party must carry out electronic authentication to submit the dossier online.
2. Data connection interruption: Where the connection between the National Business Registration Database and the National Population Database is interrupted, the registration dossier must include a copy of the valid ID Card/Citizen ID Card/Passport of the relevant individuals.
3. Status of dependent units: When the parent enterprise suspends, all of its Branches, Representative Offices, and Business Locations will also automatically switch to the suspended status. The enterprise does not need to carry out a separate procedure for each dependent unit.
4. Cases of refusal: The registration authority will refuse to issue the suspension confirmation if the enterprise falls into the following cases:
- Currently undergoing dissolution.
- Currently subject to a decision to revoke the Enterprise Registration Certificate.
- Currently in the legal status of “Not operating at the registered address.”
Procedure to resume business before the deadline
If the enterprise wants to resume operations earlier than the registered period (e.g., it registered a 1-year suspension but wants to resume after 6 months), the enterprise needs to carry out the Notification of early business resumption procedure.
- Notification deadline: At least 03 working days before the date of resuming operations.
- Dossier: Similar to the suspension dossier (replacing the suspension notification form with the business resumption notification form).
- Fee: Free of charge.
Cost of carrying out the procedure
State fees:
- Business suspension registration procedure: Fee-exempt (Under Circular 47/2019/TT-BTC).
- Early business resumption registration procedure: Fee-exempt.
Information disclosure fee: The enterprise must pay a fee to disclose the enterprise registration content on the National Portal (the fee level is as prescribed at the time of submission, usually VND 100,000).
Service fee (if hiring an external firm): Depending on the consulting firm, ranging from VND 800,000 – 1,000,000 (including the disclosure fee and dossier drafting).
Frequently Asked Questions (FAQ)
Q1: Do I need to submit a paper dossier after submitting online?
No. The process is now carried out entirely online. The result is returned as an electronic document with legal validity equivalent to a paper copy.
Q2: Is an enterprise under business suspension subject to a tax inspection?
In principle, since the enterprise has no activity during the suspension, it is rarely inspected. However, the tax authority still has the right to examine the enterprise’s compliance with tax law for the period before the suspension, or if it detects signs of “underground” business during the suspension.
Q3: What happens if the suspension period ends without a notification to resume operations?
When the registered period ends, the system will automatically change the enterprise’s status back to “Operating.” At that point, the enterprise must by default fully fulfill its tax declaration obligations and pay the business license tax. If it fails to do so, it will be subject to administrative tax penalties.
Q4: During the business suspension, can the enterprise issue invoices?
Absolutely not. By regulation, during the business suspension, the enterprise may not conduct the sale of goods or the provision of services, and therefore may not issue invoices.
Exception: The enterprise may only issue invoices to perform contracts signed before the suspension (if the customer agrees) or to issue asset-liquidation invoices to pay debts. However, this must be notified and clearly explained to the tax authority to avoid penalties.
Q5: Does an enterprise under business suspension have to pay Social Insurance (SI) for its employees?
If the enterprise and the employee agree to temporarily postpone the labor contract during the business suspension:
- If the employee takes unpaid leave of 14 working days or more in the month, the enterprise does not have to pay SI for that month.
- The enterprise must carry out the labor-reduction reporting procedure with the SI agency as soon as the suspension decision is made.
Q6: While under business suspension, can the company carry out dissolution procedures?
Yes. The law allows an enterprise to move from the business suspension status to dissolution at any time if it determines that it cannot continue operating. Note: To dissolve, the enterprise must complete the procedure to restore its tax code (if tax debts need to be handled) or fulfill its obligations to pay outstanding debts before submitting the official dissolution dossier.
Q7: What is the maximum duration of business suspension?
Under current regulations, each business suspension notification may not exceed 01 year (12 months). However, the enterprise may renew consecutively multiple times. Note that each renewal must submit a new notification dossier to the Business Registration Office at least 03 working days before the previous deadline expires.
Q8: Can new economic contracts be signed during a business suspension?
No. The nature of business suspension is to halt commercial activities. The enterprise may not sign new sale or service-supply contracts and may not participate in bidding. During this time, the enterprise may only carry out transactions to settle old debts, pay employees’ salaries, or maintain the head office (electricity, water, office rent).
CONCLUSION
Complying correctly with the business suspension notification procedure is a mandatory requirement so that the enterprise can lawfully pause its tax obligations. With the changes to the notification timing (03 days) and the electronic authentication process from 2025, enterprises need to update carefully so that their dossiers are approved quickly.
If your enterprise needs support to complete the procedure quickly and accurately under the latest 2026 regulations, contact MGI Consulting right away for a full-package solution.
See MGI support service details: Business suspension consulting service 2026